 Increasing the Black homeownership rate may not lead to improvements in the racial wealth gap, according to new research from the Roosevelt Institute, a think tank, student network, and nonprofit partner to the Franklin D. Roosevelt Presidential Library and Museum.
Authored by Zawadi Rucks-Ahidiana, the report argues that historical financial disparities and systemic racism embedded within the housing market make homeownership a risky investment for Black Americans. For example, homeownership requires wealth to both enter and maintain. Black Americans have a significantly lower median household wealth and a lower median income than White Americans, meaning they have less to invest in homeownership. Black Americans are also less likely than White Americans to receive intergenerational support when paying their mortgage down payments. And once homeownership is secured, Black homeowners have fewer liquid assets to direct toward home repairs.
The report also cites prior research on the persistent racial discrimination facing Black Americans during the home buying process. This includes a discriminatory process called steering, in which real estate agents show their clients properties in neighborhoods where their racial group is the majority. As Black neighborhoods are devalued compared to White neighborhoods, Black homebuyers are steered toward properties with lower home values and lower rates of appreciation.
Additionally, Black homebuyers face discrimination in the mortgage lending process. Compared to White borrowers, Black borrowers are more likely to be denied a mortgage. When they are approved, Black borrowers do not receive favorable rates and terms on loans compared to their White counterparts.
Furthermore, homes in White neighborhoods are typically valued higher than homes in Black neighborhoods. According to the report, research has shown these disparities exist regardless of income, with particularly large disparities between high-income homeowners. This devaluation leads to lower appreciation for homes in Black neighborhoods and thus, lower returns on investment for Black homeowners.
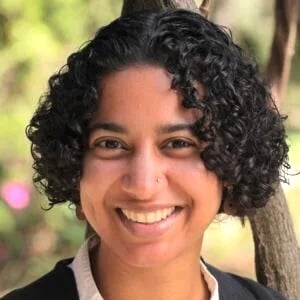
“The racism and discrimination Black homeowners face in the housing market has real consequences for their returns on homeownership and for the terms and conditions of their mortgage loans,” writes Dr. Rucks-Ahidiana, associate professor of sociology at the University at Albany in New York. “Policies and protections that go beyond fair housing law — to ensure that appraisal comps are not limited to comparable homes based on a neighborhood’s racial demographics, that steering is not limiting the homeownership opportunities that qualifying Black Americans can access, and that racial discrimination is not leading to predatory inclusion in mortgage lending — would help stabilize existing and future Black homeowners. But homeownership itself is not going to solve the racial wealth gap.”
Dr. Rucks-Ahidiana is a graduate of the University of Maryland, where she majored in environmental science and policy. She holds a master’s degree in public administration from New York University and both a master’s degree and a Ph.D. in sociology from the University of California, Berkeley. She has been a faculty member at the University at Albany since 2019.