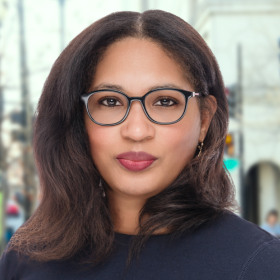
 A new policy brief authored by LaToya B. Parker, senior researcher at the Joint Center for Political and Economic Studies, examines how the requirements and eligibility rules for the Child Tax Credit (CTC) limit access to critical financial support for Black families and caregivers.
Although the “One Big Beautiful Bill Act” (OBBBA) permanently increased the maximum CTC to $2,200 per child, the legislation maintained earnings-based restrictions and capped the refundable portion at $1,700 per child. According to Dr. Parker’s analysis, these limitations prevent low-income families from accessing the full benefit. An estimated 45 percent of Black children could not receive the full CTC in 2025 because their families’ incomes were too low, compared to 39 percent of Latino children and 28 percent of children under age 17 overall.
Prior to 2025, U.S. immigrants holding an individual taxpayer identification number could claim the CTC. But OBBBA enacted a requirement that the adult claiming the child must hold a Social Security number valid for employment. Considering some 1.8 million Black children in the U.S. are immigrants themselves or the U.S.-born children of immigrants, this new requirement could significantly reduce CTC eligibility for many Black families (Dr. Parker’s analysis estimates that as many as 1.5 million children overall will see reduced or eliminated eligibility under this single provision).
Additionally, Dr. Parker notes that some 2.4 million children were raised by grandparents, other relatives, or close family friends in 2023 because their parents were unable to care for them. Black children accounted for 23 percent of these children, despite representing 14 percent of all children in the United States. The CTC tax code may not recognize these caregivers, which prevents the credit from following the child to the household actually raising them.
Based on Dr. Parker’s insights, the Joint Center offers four recommendations to Congress: make the CTC permanently fully refundable and restore a voluntary monthly-payment option, expand the qualifying-child relationship test to recognize caregivers raising children, repeal OBBBA’s Social Security number requirement for adults, and create a guardrail against hidden CTC exclusions.
“The task ahead is not to preserve a larger number in the tax code. It is to build a child credit that reaches every eligible child and follows children to the adults actually raising them,” Dr. Parker concludes. “Full refundability, periodic delivery, protections against adult-status exclusions, and caregiver recognition are not separate projects. Together, they are the income-floor infrastructure that Black children and families need to withstand economic shocks and build toward durable wealth.”
Dr. Parker leads the Joint Center’s economic policy and tax policy programs. In her work, she focuses on addressing wealth inequality and advancing policies that promote Black economic justice. She holds a Ph.D. in higher education leadership and policy studies from Howard University.